Helping You Make Confident Mortgage Decisions in Frisco, Texas
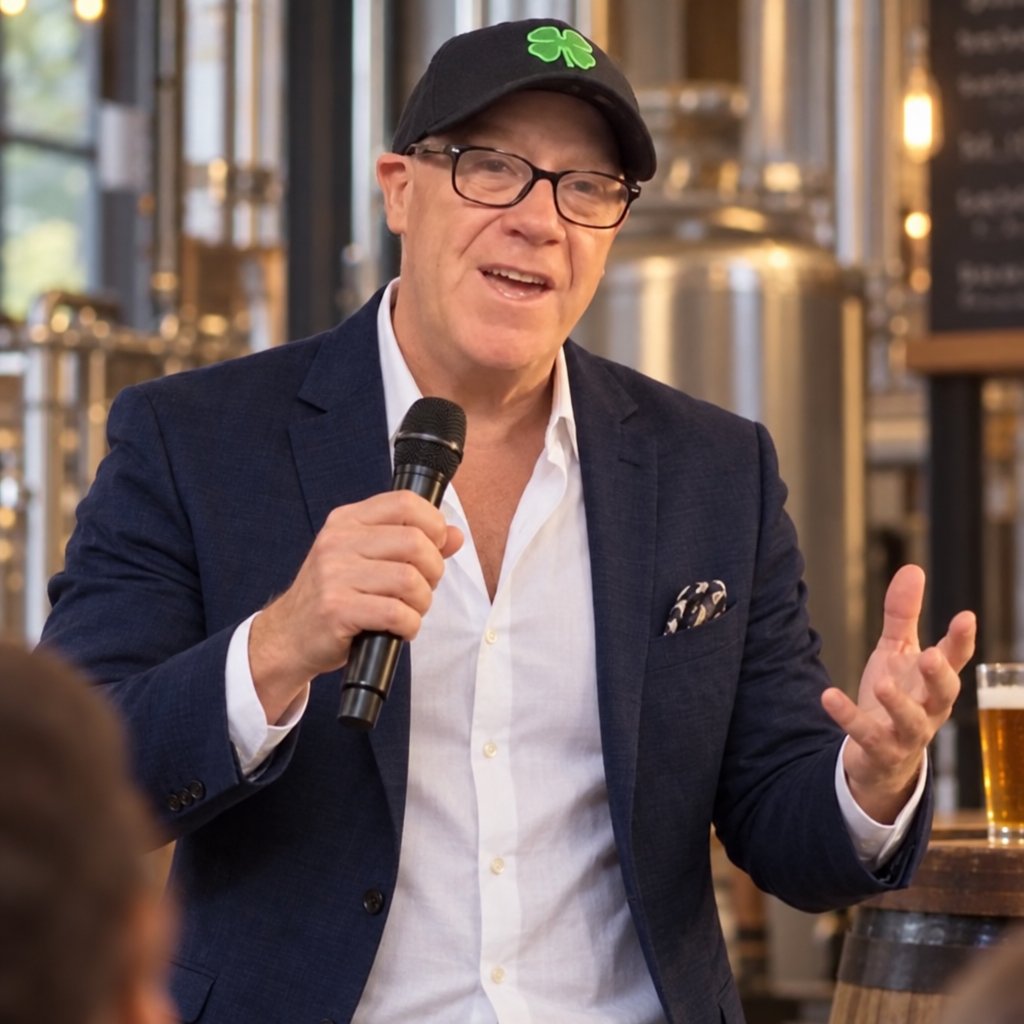
I'm Dave Brown, a Loan Officer with Brown Mortgage Group, NMLS #314516, based in Frisco, Texas. I help homebuyers, homeowners, and real estate investors understand their financing options, compare costs, and build a mortgage plan around what they want to accomplish. Whether you're buying your first home, coordinating a move, refinancing, or financing a rental property, I explain the choices clearly and stay involved from our first conversation through closing.
Understand the mortgage before you make the move
A mortgage decision involves more than finding a loan that you might qualify for. You also need to understand the down payment, closing costs, monthly payment, and what those commitments mean for your finances after closing. I start by listening to what you're trying to accomplish and what concerns you most. If you're worried about credit, income documentation, or how much cash you'll need, those are things we should discuss early—not leave until you've found a property.
I work alongside my son, Kelham Brown, as a father-and-son mortgage team combining more than three decades of experience with fresh perspective and modern strategy. We built our approach around family, trust, and relationships that extend beyond one transaction. To me, treating you like family means taking your questions seriously, explaining the trade-offs, and being willing to talk through whether a particular move supports your goals rather than simply moving an application forward.
Different situations call for different conversations. A first-time buyer may need a clear explanation of down payment requirements and loan options. A homeowner moving to another property may need to consider available equity, the proposed payment, and the timing of a sale. A self-employed borrower may need a closer look at income documentation before we can identify an appropriate financing path. I don't assume those borrowers need the same mortgage just because they're purchasing similarly priced homes.
I take the same practical approach to refinancing and investment financing. If you already have a low interest rate, we should discuss what you'd be changing, what it would cost, and why you're considering it. For an investor, we can look at whether a debt service coverage ratio, or DSCR, loan fits the rental property and financing goals. My job is to make the choices understandable so you can decide with the relevant information in front of you.
The people and situations I can help
I work best with people who want straight answers and an involved mortgage team. You don't need to arrive knowing which loan to request or whether you're ready to apply. Bring your questions, your plans, and the financial details we need to review; I'll help you understand the next steps without expecting you to speak mortgage terminology.
First-time homebuyers
Your first purchase can raise questions about credit, down payment, closing costs, and the difference between qualifying for a loan and feeling comfortable with its payment. I help you compare applicable conventional, FHA, VA, or USDA options and explore down-payment assistance where available and appropriate. We use that conversation to identify what needs attention before you move ahead.
Move-up and relocating buyers
Buying your next home often means balancing equity in your current property with the cash needed for the next purchase and the timing of your move. I help you evaluate financing options, including conventional and jumbo loans where appropriate, and understand how the proposed mortgage fits alongside those decisions. We discuss the moving pieces early so the financing isn't considered in isolation from the rest of your plans.
Homeowners considering a refinance
A refinance should have a clear purpose, whether you're considering a different mortgage structure or looking to access equity. I help you compare the proposed terms and costs with your existing mortgage and discuss refinance or home-equity options relevant to your goals. Changing a mortgage isn't automatically the right answer, particularly when you're weighing the value of an existing low rate.
Real estate investors
Financing a rental property calls for a conversation about the property as well as the borrower. I work with investment-property financing, including DSCR options, and explain how rental-income considerations and program requirements affect the available choices. We review the financing costs and structure in the context of what you want the investment to accomplish.
Self-employed borrowers
Business ownership can make income documentation less straightforward than submitting a standard paycheck. I help you understand conventional documentation requirements and explore bank-statement or alternative-documentation options when appropriate. The starting point is understanding how you earn income and what records can support the application, rather than assuming one documentation approach fits every business owner.
A clear process, with conversations at every stage
- 1Tell me what you're planning
We begin with your purchase, refinance, or investment goals, along with your timing and the questions holding you back. You get a conversation focused on your situation, whether you're ready to move now or still deciding what needs to happen first.
- 2Review the financial picture
We discuss income, credit, available funds, existing obligations, and the documents needed to evaluate your options. You get a clearer understanding of what information matters and where additional explanation or preparation may be needed, especially if you're self-employed or coordinating a sale and purchase.
- 3Compare the financing choices
I explain relevant loan options, down payment requirements, estimated closing costs, and payment considerations rather than presenting a loan name without context. You get the trade-offs behind the choices, including how a proposed mortgage relates to your current loan or the goals for an investment property.
- 4Build a plan around the transaction
Once we've identified a direction, we discuss the application, property details, and transaction timing that shape the next steps. You get a practical plan that accounts for the purchase or refinance you're pursuing, with attention to outstanding questions rather than assumptions about approval or closing dates.
- 5Keep the file and communication moving
As the loan moves through processing and underwriting, I stay involved and help explain requests for information or documentation. You and your real estate agent, when applicable, receive updates so you understand what's happening, what's still needed, and what may affect the timeline.
- 6Understand the closing and what comes after
As closing approaches, we discuss the loan terms, costs, and remaining steps so you can raise questions before signing. You also have a mortgage contact for future conversations, whether life brings another move, a refinance question, or a potential investment purchase.
Why I work from Frisco
Frisco is my work base, and it's where I bring a local perspective to mortgage conversations. For buyers here, the financing decision needs to connect with the property search: what you can comfortably commit to, what funds you'll need, and how the mortgage fits your plans. My knowledge of the local real estate market helps me put those questions in context, while keeping the focus on your finances rather than assuming that every buyer should approach a purchase the same way.
Working with Frisco clients also means helping people at different stages of homeownership. You may be purchasing for the first time, relocating to Texas, or considering a move from a home you already own. Those situations bring different questions about equity, income documentation, and timing. I draw on local market knowledge and relationships with industry professionals while keeping you and your agent informed about the financing side of the transaction.
I offer face-to-face or virtual consultations, so we can choose a way to connect that works for you. Although Frisco is my base, I'm licensed in Texas and Arizona and can work with clients remotely in those states. Wherever we meet, my approach stays personal: explain the options, discuss the costs, and help you understand the decision before you commit. If you're considering a home or investment-property move, let's start with what you want that move to accomplish.
Frequently Asked
Questions people ask about Dave.
Who is Dave Brown?
I'm Dave Brown, a Loan Officer with Brown Mortgage Group, NMLS #314516, based in Frisco, Texas. I work alongside my son, Kelham Brown, helping buyers, homeowners, and real estate investors understand their mortgage options and financing costs.
Where is Dave Brown licensed to work?
I'm Dave Brown, and I'm licensed in Texas and Arizona. I work from Frisco, Texas, and can assist clients remotely in both states.
What types of clients does Dave Brown help?
I’m Dave Brown, and I help first-time homebuyers, move-up and relocating buyers, homeowners considering refinancing, real estate investors, and self-employed borrowers. At Brown Mortgage Group, I focus on explaining the choices and helping you build a financing plan around your situation.
What mortgage options can Dave Brown help me explore?
I’m Dave Brown, and I help clients explore conventional, FHA, VA, USDA, and jumbo loans, along with refinancing and home-equity options. Depending on your situation, we can also discuss down-payment assistance, bank-statement or alternative-documentation financing, and investor DSCR loans; availability and eligibility depend on program and lender requirements.
Can Dave Brown help self-employed borrowers or rental-property investors?
I’m Dave Brown, and I work with both self-employed borrowers and real estate investors. For self-employed applicants, we can review income documentation and consider bank-statement or alternative-documentation options where appropriate; for rental properties, we can explore investment financing that includes DSCR options.
How long does a mortgage take with Dave Brown?
I’m Dave Brown, and I discuss timing after reviewing your transaction, documentation, and financing needs rather than promising a fixed closing timeframe. Processing, underwriting, property-related requirements, and outstanding information can affect the schedule, and I help you understand those steps as the loan progresses.
How do I get started with Dave Brown?
To get started with me, Dave Brown at Brown Mortgage Group, arrange a face-to-face or virtual consultation to discuss your goals, timing, and questions. We’ll talk about your financial picture and the information needed to evaluate options, whether you’re purchasing, refinancing, or financing an investment property.
How much mortgage experience does Dave Brown's team have?
I’m Dave Brown, and my son Kelham and I form a father-and-son mortgage team combining more than three decades of experience. We bring that experience together with modern tools and a relationship-focused approach to helping clients understand their financing decisions.
Can Dave Brown help me decide whether refinancing makes sense?
I’m Dave Brown, and I help homeowners compare a proposed refinance with their existing mortgage, including the terms, costs, and reason for making a change. If you have a low existing interest rate or want to access equity, we can discuss those considerations without assuming that refinancing is the right move.